

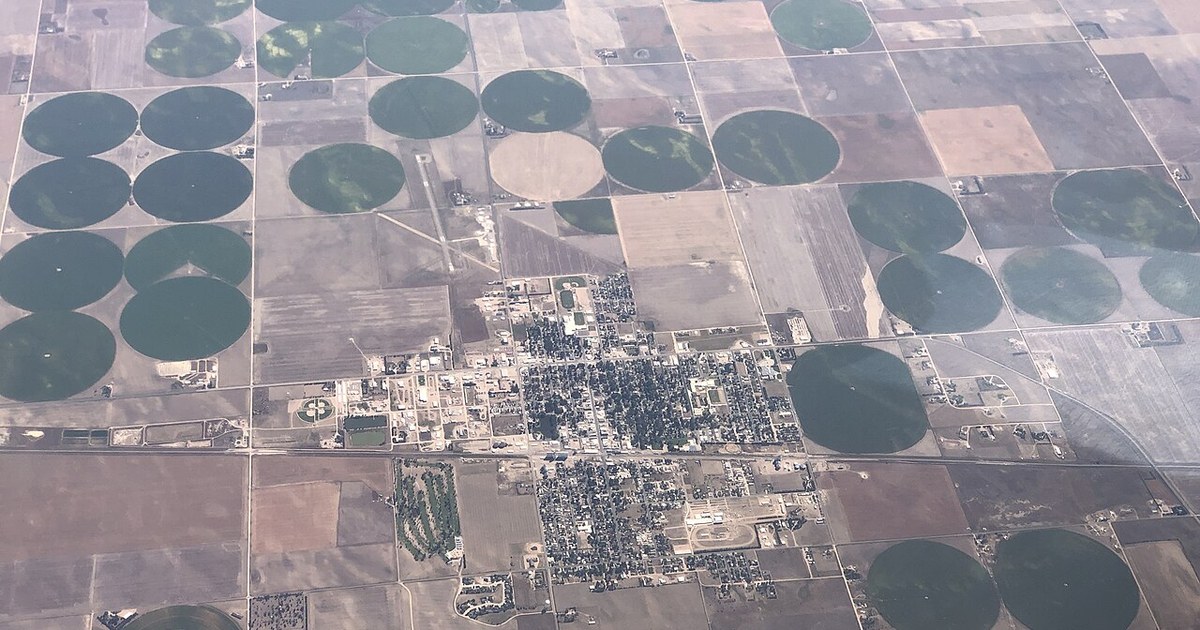
Freedom Insurance Group serves Yuma, CO with side-by-side homeowners quotes from 25+ companies.
What makes Yuma, CO unique
Yuma is about 3,596 residents, in Yuma County, within Yuma County region.
Yuma sits in Yuma County region, where day-to-day insurance shopping is shaped more by home characteristics and carrier appetite than by any single landmark.
Local housing is a mix of single-family homes typical of Yuma County region; replacement cost, roof age, and construction type still drive most premium differences block by block.
Eastern Plains properties are exposed to hail, tornadoes, and high winds typical of the High Plains.
Home insurance pricing in Yuma, CO
The typical homeowners insurance premium in Yuma, CO is about $2,457 annually for a typical local home (typical local home value about $180,000). For a $300,000 dwelling, expect around $3,053 per year; for a $600,000 home about $4,296; and for a $1,000,000 dwelling about $5,590. Freedom Insurance Group rates are often about 41% lower — near $1,450 per year for a typical home, roughly $1,801 for a $300,000 home, about $2,535 for a $600,000 home, and around $3,298 for a $1,000,000 home.
| Dwelling Coverage Limits | Average Annual Premium (incl. Windstorm & Hail Coverage) |
|---|---|
| $100,000 – $200,000 | $2,374 |
| $200,000 – $300,000 | $2,653 |
| $300,000 – $400,000 | $3,257 |
| $400,000 – $500,000 | $3,687 |
| $500,000 – $600,000 | $4,104 |
| $600,000 – $700,000 | $4,431 |
| $700,000 – $800,000 | $4,702 |
| $800,000 – $900,000 | $5,057 |
| $900,000 – $1,000,000 | $5,412 |
Band premiums are midpoints on the Yuma dwelling curve (typical local home value about $180,000). Illustrated estimates, not a quote.
Figures are 2026 market-style estimates for Yuma, CO, using a typical local home value of about $180,000. Freedom figures apply an approximate 41% savings vs the local typical premium for illustration. Your quote depends on dwelling limit, roof, deductible, claims, and carrier. Not a guarantee.
Home insurance coverage basics
- Dwelling (A): This limit pays to rebuild the structure of your home after a covered loss, and it should track current reconstruction costs in your area.
- Other structures (B): This portion applies to detached features such as a garage, shed, fence, or similar buildings that sit apart from the main house.
- Personal property (C): This coverage protects furniture, clothing, and everyday belongings inside the home, with special limits that can apply to higher-value categories.
- Loss of use (D): This coverage can help with additional living expenses when a covered claim makes the home temporarily unlivable during repairs.
- Personal liability (E): This coverage responds when you are legally responsible for bodily injury or property damage to others arising from a covered incident.
- Medical payments (F): This coverage can help with guest medical bills for injuries that occur on your property, often without requiring a formal liability claim.
Home insurance discounts in Yuma, CO
| Discount | What it means | Typical amount |
|---|---|---|
| New Home | New construction recently purchased | up to 40% |
| Age of home (5 yrs) | Newer homes | up to 26% |
| Bundle | Home and auto together | up to 25% |
| Upgrades | Electrical, plumbing, heating, roof updates | up to 20% |
| Hail-resistant roof | Class 1–4 impact roof | up to 12% |
| Claims-free | Multi-year claims-free history | up to 5% |
| Security / alarms | Monitored fire or burglar alarm | up to 4% |
| Paid in full | Pay annual premium upfront | up to 7% |
Discount availability and amounts vary by carrier. “Up to” is the high end — not a guarantee.
What affects home insurance prices in Yuma
Yuma homeowners are priced on several interlocking factors that underwriters review when they build a quote. Rebuild cost, roof age and material, and local storm or wildfire exposure tend to move the number most, while deductible choice and claims history can change the final premium as much as the carrier brand itself.
Replacement cost is the amount needed to rebuild the home with similar materials at today’s labor and supply prices. Higher rebuild estimates for Yuma properties generally raise premiums because the carrier’s maximum payout grows with that figure.
Construction type and roof details also matter: frame versus masonry walls, roof covering, and overall build quality all influence how a property performs in wind, hail, and fire scenarios that are common across Colorado.
Location risk reflects storm, hail, wildfire, and crime scores that can vary by ZIP code and neighborhood within Yuma, so two homes with similar rebuild costs may still price differently.
Fire protection considers distance to hydrants and fire stations, along with local protection class, and stronger protection profiles can support more competitive pricing.
Claims history remains a major rating input: recent claims on the property or household often increase rates for Yuma renewals and new business quotes alike.
Credit-based insurance score, where permitted by state rules, is another lever—stronger scores usually correlate with lower premiums when the carrier uses that factor.
Yuma, CO home & auto bundling
Illustrated average bundle savings — not a guaranteed quote. Actual savings depend on carriers and drivers.
| Place | 1-car bundle | 2-car bundle | 3-car bundle |
|---|---|---|---|
| Yuma, Colorado | $258 | $436 | $636 |
ZIP codes we insure in and around Yuma
80759 · 80727
