

Homeowners · Mold · Water Perils & Sublimits
Usually limited—and often excluded—unless mold results from a covered water peril and your form still allows remediation within a sublimit. Standard homeowners policies are not mold insurance. Long-term humidity, neglected leaks, and flood-related mold sit outside what most HO-3-style forms intend to pay. Sudden accidental discharge from a plumbing system can open a path for water damage and limited mold cleanup; gradual seepage and maintenance failures usually do not. Homeowners who discover fuzzy growth after months of a slow drip are often facing a maintenance problem, not a blank-check claim. Educational, not legal or medical advice. The policy is built around sudden accidental water events and limited follow-on mold handling—not years of ignored humidity.
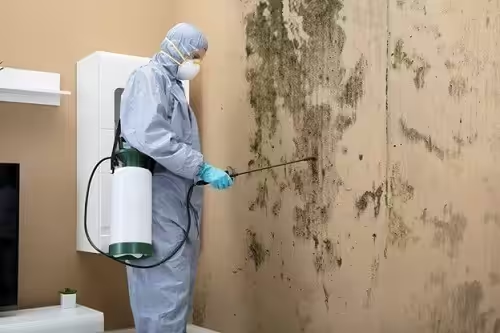
Not a claim promise: Mold language, fungi endorsements, and dollar caps vary by carrier and state. Read your exclusions and any limited fungi / mold endorsement. We do not market fake fixed-percent savings. Coverage basics: what homeowners insurance includes. If you are shopping coverage, ask what the mold sublimit is before a water event—not only after remediation invoices arrive. If your form has no limited fungi coverage, do not assume a neighbor’s sublimit applies to you.
1. How mold usually sits on a homeowners form
| Situation | Typical treatment (high level) |
|---|---|
| Mold from a sudden, accidental plumbing burst that you promptly report and dry | Water damage may be covered; mold remediation often capped by a fungi/mold sublimit if the endorsement/form allows it |
| Mold from a slow leak, poor ventilation, or deferred maintenance | Commonly excluded as wear, tear, deterioration, or repeated seepage / continuous leakage |
| Mold after a flood or storm surge | Homeowners excludes flood; NFIP/private flood forms have their own rules—do not assume HO mold language applies |
| Standalone “mold everywhere” with no covered water event | Typically not covered |
The pattern across rows is consistent: sudden covered water first, then limited mold handling if the form allows it—not mold as a free-standing peril. That is why adjusters ask when the leak started, when you noticed it, and what you did to dry the area. Honest timelines help; vague “it’s been a while” answers push the fact pattern toward continuous leakage exclusions.
2. Sublimits and remediation
Limited fungi / mold coverage
Many policies add a small dollar cap (sometimes a few thousand dollars) for testing, removal, and related tear-out when mold follows a covered water loss. That cap is not a blank check for whole-house remediation. Confirm the number on your endorsements rather than assuming a neighbor’s limit matches yours.
What the water claim pays
Repairing sudden water damage to drywall, flooring, and belongings can be separate from the mold sublimit. Adjusters may split “water” vs “mold” costs carefully. Clear invoices help that split stay fair instead of dumping every cost into the smaller mold bucket. Ask remediation vendors to itemize water dry-out work separately from mold-specific testing and removal when they can.
- Ask whether your policy includes a limited fungi endorsement and what the dollar limit is
- Prompt mitigation (water extraction, drying) matters for both coverage and health—document timelines
- Related appliance/water theme: water heater coverage
Keep photos of the water source, moisture readings if vendors take them, and a simple timeline of when you shut off the water and called for drying. That paperwork supports the “sudden and accidental” story better than a verbal summary weeks later.
3. Prevention beats claims rhetoric
- Fix drips, AC condensate lines, and roof leaks early
- Run bathroom / kitchen ventilation; watch crawlspaces and basements after storms
- In Texas heat and humidity, do not leave wet carpet or drywall “for later”
- In Colorado freeze seasons, watch ice dams and pipe rooms; dry promptly after melt events
- Keep maintenance records—helpful if a carrier questions continuous leakage
State hubs for broader home context: Texas home insurance · Colorado homeowners insurance · homeowners insurance Texas. Prevention is not a slogan here—it is how you avoid both health problems and the continuous-leakage exclusion conversation. A cheap plumbing repair today is almost always cheaper than arguing about mold after months of damp drywall.
4. Practical claim steps (if water came first)
- Stop the source of water when safe; photograph before major demo
- Call your agent with the water event facts—not a pre-labeled “mold claim”
- Ask what mitigation vendors your carrier prefers and what the mold sublimit is
- Separate invoices for water repairs vs mold remediation when possible
- If flood was involved, open the flood claim path—not only the homeowners policy
Leading with “mold claim” before explaining the water event can send the conversation straight to exclusions. Lead with the sudden water facts, then ask how mold remediation is handled under your endorsement. Your agent can help translate the sublimit and any waiting or mitigation requirements before tear-out gets ahead of the claim.
FAQ
Does homeowners insurance cover mold damage?
Often only in a limited way, and usually only when mold follows a covered sudden water peril. Standalone or maintenance-related mold is commonly excluded. Read your form’s fungi language rather than relying on a general internet answer.
Is there a mold sublimit?
Many policies include a limited fungi/mold dollar cap. Confirm the number on your endorsements. Caps are often modest relative to whole-house remediation invoices, which is why prevention and prompt drying matter so much. Knowing the number in advance also helps you decide how aggressively to mitigate out of pocket while the claim is opening.
What about mold after a flood in Texas?
Flood is excluded from standard homeowners. Use NFIP or private flood for flood-related losses; mold handling follows that form, not HO assumptions. Opening only a homeowners claim after a flood event can waste critical time.
Does Colorado treat mold differently?
Core exclusions are similar; local water causes (ice dams, melt, plumbing) change the fact pattern more than the mold heading itself. Dry promptly after melt or pipe events the same way Texas homeowners dry after a summer plumbing burst.
Should I wait to dry the house before calling?
No—mitigate promptly and document. Delaying drying can hurt both your home and a carrier’s view of continuous damage. Call while you are arranging extraction, not after mold has had weeks to grow.
What happens if my home insurance claim for mold is denied?
Ask for the denial in writing with the policy language it relies on. TDI notes that most policies don’t cover mold removal except to repair damage caused by a covered risk, so the key question is usually whether a sudden, covered water event caused the mold. If you disagree, send documentation such as a plumber’s report, request a re-inspection, and you can file a complaint with the Texas Department of Insurance.
Where can I find home insurance that covers mold damage?
Ask about a mold endorsement or higher mold sublimit, and compare forms: an HO-5 policy covers more causes of loss for belongings than an HO-3, but both usually limit mold. Keep your heating and air conditioning (HVAC) system maintained, since condensation problems are a common cause of mold that policies treat as maintenance.
Sources & further reading
- EPA — Mold (health/prevention context, not insurance advice)
- Freedom — Homeowners coverage overview
- Freedom — Texas home insurance
- Freedom — Homeowners insurance Texas
- Freedom — Colorado homeowners insurance
- Freedom — Water heater coverage
- Freedom — Texas flood insurance
- TDI — Homeowners insurance guide.
