

Texas · Auto Insurance · Physical Damage
Comprehensive vs collision for Texas drivers is about how your own vehicle is damaged—not whether you owe the other driver. Collision pays after a crash or rollover with another vehicle or object. Comprehensive—often labeled “other than collision” (OTC) on the policy form—pays for many non-crash perils such as theft, vandalism, hail, fire, flood, glass, falling objects, and many animal strikes. Neither replaces liability. Texas’s minimum liability rules (commonly summarized as 30/60/25) address injury and property damage you cause to others; they do not require comprehensive or collision. Understanding which coverage responds before a claim lands makes deductible choices and “full coverage” shopping much clearer, especially when a lender or lessor is also watching the declarations page.
Educational only: Texas personal-auto forms, glass options, and underwriting change by carrier. Your declarations page and the Texas Department of Insurance (TDI) guidance control. Freedom Insurance Group is an independent agency. This is not legal advice. Always confirm animal-strike wording, glass deductibles, and actual cash value (ACV) settlement rules on the form you actually buy—not on a generic blog example.
Comprehensive (other than collision)
Comprehensive is first-party physical damage for covered non-collision losses, subject to your deductible and actual cash value (ACV) settlement rules. In plain language, it is the coverage that steps in when something happens to your car that is not a typical traffic crash. Everyday Texas examples include:
- Theft and attempted theft: Stolen vehicle or damage from a break-in
- Vandalism: Keying, smashed windows, graffiti
- Weather: Hail, wind-blown debris, flood or rising water as the form defines it—common across North Texas hail corridors and Gulf-adjacent storms
- Fire and explosion: Vehicle fire not caused by collision
- Animal impact: Many deer or livestock strikes are treated as comprehensive—confirm your form
- Glass: Windshield and window breakage; some carriers offer a separate glass deductible option
- Falling objects: Tree limbs, parking-lot debris, rockfall
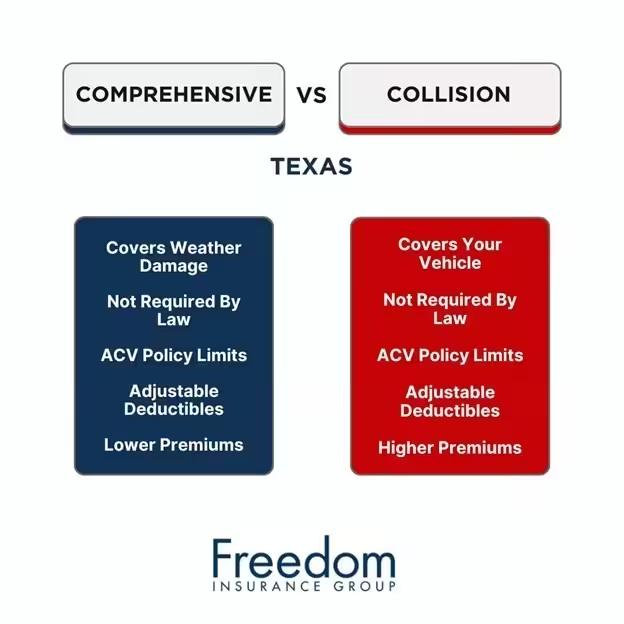
Because hail and theft are frequent conversation topics in Texas shopping, comprehensive often feels more “real” to drivers than a theoretical coverage line. Still, settlement is usually ACV minus the deductible—not a brand-new replacement vehicle—unless you carry a specific endorsement that says otherwise. Quiet related hub: Texas comprehensive insurance.
Collision
Collision pays to repair or replace your covered auto after a crash with another vehicle or object, or after an upset/rollover, subject to the collision deductible—whether or not you were at fault. If you are at fault, your liability coverage may also respond to the other party’s injuries and property; collision is what addresses your own sheet metal. Hit a parked car, a guardrail, a median, or a ditch while avoiding traffic? Collision is usually the coverage in play (confirm the form). Single-vehicle losses on wet highways and multi-car pileups on interstate corridors both typically land in collision for your own vehicle’s damage, even though the liability conversation with the other drivers can look very different. At-fault rating and surcharge conversations are separate from whether collision pays your sheet metal—both can matter after the same crash.
Quiet related hub: Texas collision coverage. If you are comparing “full coverage” quotes, ask each market to show collision and comprehensive deductibles on the same worksheet so you are not ranking premiums that hide different retained risk.
Comprehensive / OTC
Your car, non-crash perils (theft, hail, vandalism, animals, glass), subject to the comprehensive deductible. Think “something happened to the car” that was not a typical crash with another vehicle or object in traffic.
Collision
Your car after a crash or rollover with another vehicle or object, subject to the collision deductible. Think “the car hit something or rolled” whether or not you were at fault.
| Scenario | Likely coverage | Watch for |
|---|---|---|
| You rear-end another car on I-35 | Your liability + your collision | Separate deductibles; at-fault rating |
| Car stolen from a Houston or Dallas lot | Comprehensive | ACV settlement; GAP if you owe more |
| Hail dents the roof in North Texas | Comprehensive | Deductible; prior damage; ACV vs repair |
| Deer strike on a rural highway | Often comprehensive | Confirm animal wording on your form |
| You slide into a guardrail in rain | Collision | Collision deductible; single-vehicle claim |
| Someone keys your door overnight | Comprehensive | Whether repair cost exceeds deductible |
Deductibles and when each applies
Comprehensive and collision each carry their own deductible. A higher deductible usually lowers premium but raises what you pay after every covered claim of that type. Some Texas drivers keep a lower comprehensive deductible if hail or theft feels more likely than crashes in their ZIP, while using a higher collision deductible—or the reverse. Glass may have its own option; ask whether windshield claims waive or reduce the comprehensive deductible under your form. The right split is personal: it should match cash you can actually spend after a loss, not only the lowest monthly payment on a quote screen.
Honest pricing note: premium tracks vehicle value, garaging ZIP, driver record, prior claims, and carrier appetite. No fixed “raise deductible, save X%” promise applies to every Texas garage. Dropping both coverages on a paid-off older car can make sense if you can self-insure the ACV; it is a cash-flow decision, not a universal rule. Before you drop physical damage, compare one year of comprehensive-and-collision premium to the car’s realistic market value and to how quickly you could replace the vehicle from savings.
Texas framing: 30/60/25 vs “full coverage”
Texas’s minimum liability package is commonly described as 30/60/25—$30,000 bodily injury per person, $60,000 bodily injury per accident, and $25,000 property damage. Those limits protect others when you are at fault; they do not repair your car after a crash or pay for hail/theft. Everyday “full coverage” usually means liability plus collision plus comprehensive, often with uninsured/underinsured motorist (UM/UIM), personal injury protection (PIP), and maybe rental reimbursement. Lenders and lessors almost always require comprehensive and collision until the loan or lease ends. Saying you have “full coverage” without naming deductibles and physical-damage limits still leaves a lot of detail on the table—ask for the declarations page breakdown whenever someone uses that phrase. Drivers who recently paid off a loan should also revisit whether keeping both physical-damage coverages still matches the car’s value and their emergency fund, rather than leaving lender-era deductibles in place by habit alone.
For the broader map, see car insurance in Texas, Texas full coverage, and Texas liability car insurance. Product overview: Texas auto insurance.
How to choose without hollow discount claims
- Confirm whether a lender or lessor requires both comprehensive and collision.
- Match both deductibles across every quote before ranking premiums.
- Ask about glass deductible options and rental reimbursement after a physical-damage claim.
- If you owe more than ACV, ask about GAP separately—it is not the same as comprehensive or collision.
- On a paid-off older car, compare annual physical-damage premium to the car’s realistic ACV and your emergency fund.
- Ignore banners that promise a fixed giant savings percentage; compare real quotes with identical inputs.
When you compare quotes, keep the same vehicles, drivers, garaging ZIP, liability limits, and both deductibles locked in. Otherwise a “cheaper” number may simply be thinner physical damage or a higher deductible you cannot comfortably pay after hail season.
FAQ
Does Texas require comprehensive or collision?
No. State minimum rules focus on liability (often summarized as 30/60/25). Lenders and lessors usually require both physical-damage coverages. Keeping continuous liability coverage still matters for registration and shopping even when you drop comprehensive and collision on a paid-off older car.
Is a deer strike comprehensive or collision?
Often comprehensive (OTC), but confirm the form. Classification disputes happen—ask before you need a claim. Livestock and wildlife wording can vary slightly by carrier, so do not assume every animal impact is treated the same way on every Texas personal-auto form.
Can I buy one without the other?
Sometimes, especially on a paid-off vehicle. Lenders typically require both. Shopping one without the other changes the risk you retain. If you keep only comprehensive, you are still self-funding crash damage to your own car; if you keep only collision, hail and theft remain on you.
Will comprehensive pay for a brand-new car after theft?
Settlement is typically actual cash value minus deductible, not a new-car replacement, unless you have a specific endorsement. Ask about new-car replacement or GAP if you finance. GAP addresses a loan balance above ACV; it is a separate conversation from comprehensive itself.
Where can I learn more?
Start with car insurance in Texas, comprehensive, and collision.
