

Homeowners · Mortgage Escrow · Multi-State (TX Notes)
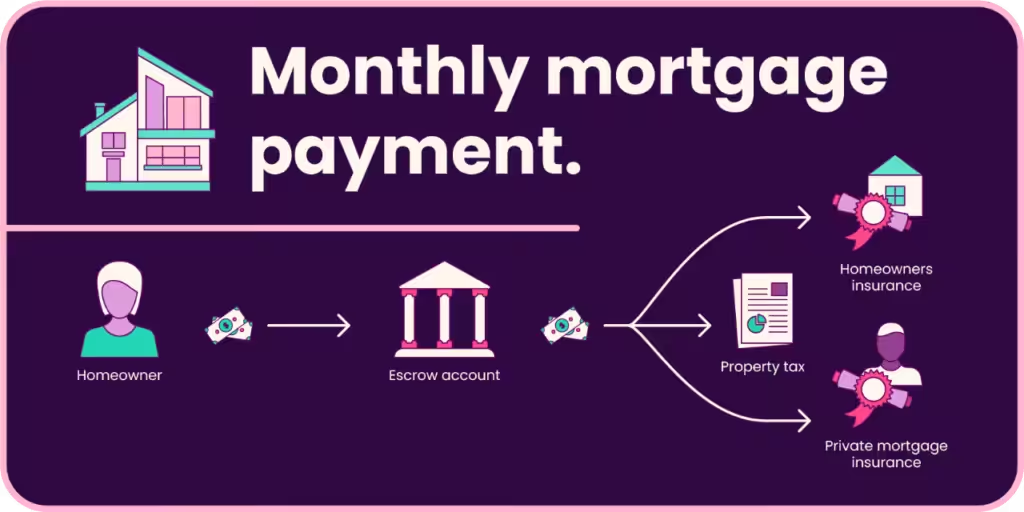
How does mortgage escrow work—and how does it pay your home insurance? Many lenders collect a monthly share of estimated annual taxes and homeowners insurance into an escrow (impound) account, then pay the insurer and taxing authorities when bills are due. When a renewal premium jumps after hail season or a rebuild-cost update, the next escrow analysis letter is often where homeowners first feel the change in their monthly payment. Understanding escrow analysis, shortages, and force-placed insurance helps you avoid surprises when premiums change. Educational overview for homeowners—not mortgage, tax, or legal advice.
Educational only. Loan documents, Real Estate Settlement Procedures Act (RESPA) escrow rules for many federally related mortgages, and your servicer’s practices control timelines. Freedom Insurance Group can help with the insurance side of escrow bills; we do not service mortgages or give lending advice.
1. What an escrow account is for
At closing—or when a lender later requires it—the servicer estimates the next year’s property taxes and homeowners premium, divides by twelve (often with a cushion), and adds that amount to your monthly principal and interest. Money sits in the escrow account until tax and insurance due dates. The goal is to make sure taxes and insurance stay current so the lender’s collateral stays protected. From the homeowner’s seat, escrow is a budgeting tool and a compliance tool at the same time: it spreads large annual bills into monthly pieces and gives the servicer a way to confirm the dwelling policy has not lapsed.
- Insurance: Servicer pays the homeowners carrier (or confirms you paid, depending on setup).
- Taxes: Servicer pays county/city/school bills when due.
- Cushion: Many loans allow a limited surplus so one late bill does not empty the account.
If your loan does not require escrow, you are still responsible for paying the carrier and the taxing authorities on time. Waiving escrow does not waive the mortgage’s insurance requirements—it only changes who writes the check and when. Homeowners who pay annually out of pocket should still calendar the renewal date and keep the mortgagee clause current, because a missed payment can trigger the same force-placed path an escrowed loan would see after a lapse.
2. How the insurance premium gets paid
Annual or installment bills
Carriers often bill annually. The servicer receives the renewal invoice (or you forward it), pays from escrow, and keeps proof of coverage on file. If the carrier bills you directly by mistake, forward the invoice quickly rather than waiting for a force-place warning.
Mortgagee clause
Your declarations page usually lists the lender as mortgagee. That clause directs the insurer to notify the lender of cancellation and often puts the lender on dwelling claim checks. Exact mortgagee name and loss-payee address must match what the servicer expects.
When you change carriers or refinance, give the new agent the exact mortgagee name and address the servicer requires. Mismatched mortgagee clauses are a common reason escrow payments bounce or force-place letters go out. Texas shoppers can start with the Texas homeowners hub; Colorado, Missouri, and Tennessee clients use the same escrow mechanics with state-specific forms. After a refinance, confirm the new servicer’s mortgagee clause wording before the next renewal invoice goes out—old lender language on a new loan file is a frequent paperwork snag.
3. Escrow analysis, shortages, and surplus
At least annually on many loans, the servicer runs an escrow analysis: compares what was collected to what was paid, projects the next year, and adjusts your monthly payment. If insurance or taxes rose, you may see:
- A higher monthly escrow portion going forward
- A shortage amount due in a lump sum or spread over months
- Occasionally a surplus refund or credit if too much was collected
Premium increases after hail seasons, rebuild-cost updates, or carrier changes are normal triggers. Ask your agent for the renewal premium early so you can warn the servicer before the analysis letter arrives. Reading the analysis line by line also helps separate an insurance jump from a property-tax jump—both can raise the same monthly payment without either one being a “mystery fee.” If you just switched carriers, ask whether a refund of unused premium from the old policy and the new annual bill will hit escrow in the same analysis cycle—timing mismatches are a common reason a “similar premium” still produces a shortage letter.
| Situation | What homeowners often see |
|---|---|
| Premium up at renewal | Higher monthly escrow; possible shortage |
| Switched carriers mid-year | Proration, refund of unused premium, new bill to escrow |
| Policy cancelled / lapsed | Force-placed insurance risk (usually expensive) |
| Claim check for dwelling | Often payable to you and the mortgagee; lender may hold funds in repair escrow |
4. Force-placed insurance—why it matters
If the servicer cannot confirm active homeowners coverage that meets loan requirements, it may buy force-placed (lender-placed) insurance and charge you. Those policies are typically far more expensive, cover the lender’s interest more than yours, and can omit or limit contents and liability. Prevention beats cure: keep proof of insurance current, answer mortgagee requests quickly, and never let a renewal lapse while you “shop around” without a binder in place. Shopping is fine—just keep continuous coverage documented while quotes are in progress.
Texas note: After storms, claim activity and roof underwriting can change renewals quickly. Coordinate carrier changes with your servicer so escrow has a continuous policy on file. Claim process overview: filing a homeowners claim. If a non-renewal letter arrives, start replacement coverage early enough that the new declarations page reaches the servicer before the old policy ends.
5. Practical habits that keep escrow smooth
- Save renewal declarations and email them to the servicer if the carrier does not auto-notify.
- When shopping quotes, match dwelling limits and deductibles the loan requires—some loans restrict low liability limits or certain deductibles.
- If your monthly payment jumps, read the escrow analysis line items before assuming the rate alone caused it (taxes often move too).
- On dwelling claims, expect the lender on the check; ask about repair draws before signing payment-direction forms.
- Questions about coverage design belong with a licensed agent; questions about payment amounts belong with the loan servicer.
A short habit that saves headaches: when you bind a new homeowners policy, send the declarations page and mortgagee clause to the servicer the same day and keep the confirmation email. That paper trail is often faster than arguing with an automated force-place notice weeks later. If the servicer uses a portal upload, save a screenshot of the confirmation along with the PDF declarations page. On dwelling claims, ask early whether the lender will require repair draws or inspections before releasing its portion of a settlement check—those steps affect how quickly contractors get paid even when coverage is not in dispute.
FAQs
Can I pay my home insurance myself instead of escrow?
Sometimes, if the loan and servicer allow waiver of escrow (often after a certain equity or payment history). Rules vary widely—ask the servicer, not only the agent. Even with a waiver, the loan usually still requires continuous hazard coverage that meets its guidelines.
Why did escrow go up when my “rate” felt flat?
Taxes, cushion rebuilding after a shortage, or a mid-year carrier change can raise the monthly amount even if the new premium looks similar to last year’s. Compare the analysis worksheet to last year’s paid amounts before assuming the insurer alone caused the jump.
What is force-placed insurance?
Coverage the lender buys when it cannot confirm your policy. It protects the lender’s interest and is usually costly—restore voluntary coverage quickly if it appears. Ask the servicer what proof they need to cancel force-placed coverage and refund any overlapping premium.
Does escrow pay liability or umbrella premiums?
Escrow typically handles the required homeowners (or hazard) policy. Separate umbrella or scheduled personal property invoices are often your responsibility unless the servicer specifically escrows them. Confirm rather than assuming every policy on your household file rides inside the impound account.
