

Colorado · Denver Metro · Lifestyle & Risk
Is Denver a good place to live? For many households it is. The city offers jobs, easy outdoor access, and a real urban core within a short drive of the foothills. It is also a Front Range market with high housing costs, regular hail seasons, wildfire risk where neighborhoods meet open brush and forest (what planners call the wildland–urban interface), and auto insurance pricing that reflects busy metro traffic. This is a balanced overview for people weighing a move or a longer stay. It is not a real estate sales pitch, and it folds in the insurance questions Coloradans actually face.
Educational only, not a relocation decision or coverage determination. Neighborhood fit, commute, schools, and budgets are personal. Insurance companies differ in how willing they are to write homes with hail-prone roofs or homes near brush. Confirm current Colorado insurance rules with the Colorado Division of Insurance (the state agency that regulates insurers) and check your declarations page, the summary page of your policy that lists coverages, limits, and deductibles.
1. What people usually like about Denver
Denver’s appeal is less about any single “best city” ranking and more about a package of advantages that work together:
- Outdoor access: parks and trails inside the metro, and for many weekends a short drive toward the foothills and ski country
- Job and industry mix: healthcare, technology, energy, aerospace, hospitality, and government and education employers spread across the metro
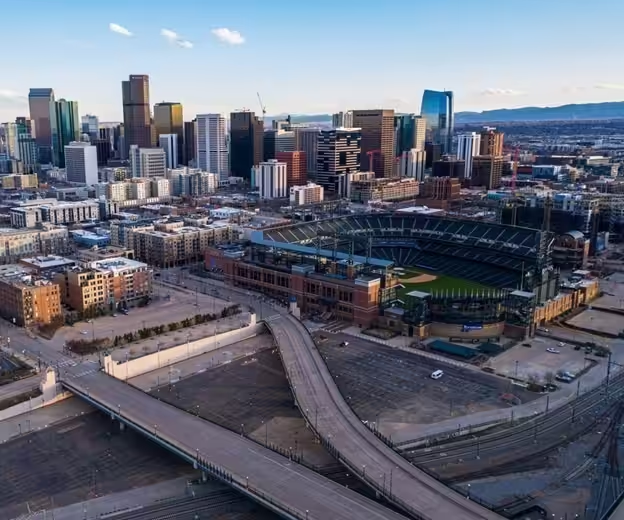
- Urban and neighborhood variety: denser city cores, older neighborhoods built along former streetcar lines, and suburban rings, each with a different style and age of housing
- Four seasons with plenty of sun: a dry climate and mountain views, with winter storms and summer thunderstorms in the mix
Whether that package is “good” for you depends on your income, your housing budget, your tolerance for growth and traffic, and how much you will actually use the outdoors. Someone who hikes or skis most weekends may find the trade-offs easy to accept. Someone who mostly stays in town may weigh the housing costs more heavily. For broader context on relocating, see moving to Colorado.
2. Cost of living: housing first, then the rest
Housing is usually the largest line item in a Denver budget. Purchase prices and rents in the Denver–Aurora–Lakewood metro area have long run above many inland United States markets. When you build a realistic monthly budget, include:
- Mortgage or rent, plus homeowners association fees or metro district fees where they apply (metro districts are special taxing districts that fund roads, water, and other infrastructure in many newer Colorado subdivisions)
- Utilities, including heating in winter and cooling during summer heat waves
- Transportation: commute length, parking, and whether you will rely on the Regional Transportation District buses and light rail or run a household with more than one car
- Insurance: homeowners, condo, or renters coverage plus auto, and sometimes an umbrella policy for extra liability protection
Do not treat a national “cost of living index” as your personal budget. Housing prices in a specific ZIP code, the length of your commute, and the deductibles you choose on your insurance move the numbers far more than any citywide slogan. Two families earning the same income can have very different experiences depending on whether they rent close to work or buy a larger home farther out.
Often a strong fit
- You want trail and mountain access without leaving a metro area
- A dual-income household can absorb Front Range housing costs
- You are comfortable with growth, construction, and traffic
- You will shop insurance before closing on a home or signing a lease
Harder fit for some
- A fixed income set against metro housing costs
- Allergy or air quality sensitivity during wildfire smoke days
- A need for a quiet small-town pace without suburban sprawl
- An older roof, a history of hail claims, and thin emergency savings
3. Hail, roofs, and the reality of homeowners insurance
The Front Range sees frequent severe thunderstorms, and hail can damage roofs, siding, windows, and vehicles in a single afternoon. That does not make Denver “unlivable.” It means homeowners need to plan for it in a few specific ways:
- Roof age, roofing material, and prior claims matter when you buy or renew homeowners coverage, and an older roof can affect both your price and how a roof claim is paid
- Insurance companies may use percentage wind and hail deductibles (a deductible calculated as a percentage of your dwelling coverage rather than a flat dollar amount) or stricter underwriting in hail-prone ZIP codes
- Comprehensive auto coverage, not the homeowners policy, is how most households handle hail dents on their cars
The percentage deductible point deserves attention. On a home insured for a large dwelling amount, even a small percentage can turn into thousands of dollars out of pocket after a storm, so make sure you know the actual dollar figure before you need it. Shop coverage with realistic dwelling limits (enough to rebuild at today’s construction costs) and a deductible you can actually fund from savings. For a Colorado homeowners overview, see homeowners insurance in Colorado. For thinking about coverage gaps, see Colorado insurance riders.
4. Wildfire and the wildland–urban interface, even if you live “in the city”
Most Denver metro addresses are not deep forest lots. Still, the foothills and mountain communities west of the city sit in or near the wildland–urban interface, and regional smoke can affect air quality across the metro after large fires. If you are looking at foothills or canyon homes, keep these points in mind:
- Fire is usually a covered peril on a homeowners policy that is already in force, but getting or keeping a policy at an address next to brush can be the harder conversation
- Mitigation, such as defensible space around the house, a fire-rated roof class, and details that resist wind-blown embers, helps your application; it is not an unsupported percentage discount coupon
- Mudflows and landslides after a fire are often treated as different perils, so do not assume every hillside problem that follows a fire is automatically covered by a standard homeowners policy
If a mountain-adjacent home is on your list, ask an agent for underwriting feedback early, before you are emotionally committed to the listing. Knowing whether insurance companies will write the address, and at what deductible, is part of knowing whether the home is affordable. Practical reading: Colorado wildfire insurance and the product hub Colorado wildfire insurance service. Also see Colorado wildfire overview.
5. Auto insurance in a growing metro
Denver driving mixes interstate commuting, winter storms, and urban density. Auto premiums reflect your rating territory, your driving record, the vehicle, and the coverages you choose, not a city slogan. If you commute along the Interstate 25 or Interstate 70 corridors, or you park outdoors during hail season, talk through your liability limits, uninsured motorist coverage (which protects you when the at-fault driver has no insurance or too little), and your comprehensive and collision deductibles. Outdoor parking in particular makes comprehensive coverage more important, since hail damage to a car falls under comprehensive. Start with Colorado car insurance, Colorado car insurance options, and comprehensive coverage in Colorado.
The table below connects common Denver lifestyle choices to the insurance questions worth asking about each one.
| Lifestyle theme | Insurance angle to check | Why it matters |
|---|---|---|
| Buying a house in the metro | Dwelling limits, roof age, wind and hail deductible | Hail and roof claims are a basic part of how insurers evaluate Front Range homes |
| Foothills or mountain-adjacent home | Wildfire risk score, mitigation, and whether insurance companies want to write the address | Placing coverage in the wildland–urban interface can be harder than for a flat suburban lot |
| Condo or townhome | Condo unit-owner policy (the standard form called HO-6) versus the association’s master policy; loss assessment coverage | The association’s coverage and your unit policy must fit together without gaps |
| Renting | Renters insurance for your belongings plus personal liability | The landlord’s policy usually does not cover your belongings |
| Daily driving and outdoor parking | Auto liability limits plus comprehensive coverage | Metro traffic and hail both show up in real claims |
6. A practical “should we move or stay?” checklist
If you are on the fence, working through these steps in order tends to surface the real costs and trade-offs before you sign anything:
- Budget housing honestly: purchase price or rent, homeowners association and metro district fees, and a maintenance reserve for roofs and heating, ventilation, and air conditioning systems.
- Test the commute: drive or ride transit along your likely route at rush hour before you commit.
- Walk the neighborhood: notice noise, parks, how the area handles drainage and flooding, and which streets stay shaded and icy in winter.
- Price insurance early: get homeowners, condo, or renters quotes and auto quotes using the ZIP code and the roof and vehicle details you actually have.
- Ask about wildfire exposure and hail: if the address sits next to brush or the roof is aging, get underwriting feedback before you fall in love with the listing.
FAQs
Is Denver a good place to live for families?
Many families thrive on the parks, youth sports, and outdoor weekends. School quality and commute length vary by suburb and neighborhood, so research school districts and after-school logistics alongside housing costs.
Is Denver expensive compared with other Colorado cities?
The metro often costs more for housing than smaller Front Range or mountain towns. Compare your actual job offer, how much remote work flexibility you have, and the type of housing you want, rather than a single statewide average.
Does living in Denver mean high home insurance?
Premiums and deductibles follow the roof, claims history, construction type, and weather and underwriting patterns at the ZIP code level. There is no guarantee that every Denver address is “expensive.” Hail and older roofs are common starting points in the conversation.
Should wildfire worry me if I live inside the city?
Dense city blocks are very different from foothills lots in the wildland–urban interface. Still, regional smoke, and friends or family who live in brush zones, make it useful to understand wildfire coverage. Addresses next to brush need a dedicated underwriting conversation. See wildfire insurance guidance.
What should I insure first when I arrive?
Put homeowners, condo, or renters coverage in place before you move your belongings in, and update your auto policy with the Colorado ZIP code where the car will be kept. Add an umbrella policy if your liability limits and assets call for it.
Sources and further reading
- Colorado homeowners insurance
- Colorado car insurance
- Colorado car insurance options
- Colorado wildfire insurance guide
- Colorado wildfire insurance hub
- Colorado wildfire overview
- Comprehensive car insurance in Colorado
- Colorado insurance riders
- Moving to Colorado
- Cheapest cars to insure in Colorado
- Colorado insurance companies context
- Colorado Division of Insurance
- Ask an agent
