

Texas · Auto Insurance · Liability vs Full Coverage
Liability vs. full coverage in Texas is a comparison between the state’s financial-responsibility floor (bodily injury and property damage you cause others) and a broader stack that also protects your vehicle through collision and comprehensive. Bodily injury (BI) pays for others’ injury costs when you are liable; property damage (PD) pays for others’ vehicle and property repairs—both up to your limits. “Full coverage” is everyday language—not a single statute-defined product. This guide is educational, not legal advice. The practical work is reading your declarations, matching limits across quotes, and deciding which risks you keep and which you transfer to the policy.
Educational only—not legal advice. Confirm current financial-responsibility rules with the Texas Department of Insurance auto insurance guide and your declarations page. Minimum limits can change; your policy—not a blog—controls what you bought.
1. Liability (BI/PD): what Texas’s floor usually means
Liability coverage pays for bodily injury (BI) and property damage (PD) you are legally responsible for in a crash—other people’s medical bills, their vehicle repairs, and related damages subject to your limits. Texas drivers commonly see split limits described as 30/60/25:
- $30,000 bodily injury per person
- $60,000 bodily injury per accident
- $25,000 property damage per accident
Those figures are a floor, not a recommendation sized to every household’s assets. Hospital care and vehicle replacement costs routinely exceed statutory minimums. Context: what Texas car insurance covers and limit literacy via insurance limits.
Split limits mean each number applies separately: one person’s injury claim can use the per-person BI limit, multiple injured people share the per-accident BI limit, and PD has its own cap. If a claim exceeds those caps, you may be personally responsible for the difference. That is why many Texas households raise BI/PD above 30/60/25 even when they keep a modest physical-damage stack.
Continuous liability coverage also matters for Texas financial-responsibility rules and for future underwriting. A short lapse while you decide whether to buy collision can still appear when the next carrier reviews your history—even if you never filed a physical-damage claim during the gap.
2. What “full coverage” usually bundles
In consumer language, full coverage typically means liability plus:
- Collision — damage to your car from a crash with another vehicle or object, subject to a deductible.
- Comprehensive — non-collision physical damage such as theft, vandalism, glass, hail, flood, or hitting an animal—again usually with a deductible. Hail is a real Texas exposure, not a footnote.
People often add personal injury protection (PIP), uninsured/underinsured motorist (UM/UIM), roadside, and rental reimbursement. Personal injury protection can help with medical bills and related expenses within policy terms, often regardless of fault. Uninsured motorist / underinsured motorist coverage helps when the at-fault driver has no insurance or not enough. Those options are not automatically included just because someone said “full coverage” on the phone—read the declarations. Parallel framing: how comprehensive protects Texas drivers.
A deductible is what you pay out of pocket before collision or comprehensive responds. Liability usually has no deductible in the same sense; your BI/PD limits are ceilings on what the policy pays others, not a first-dollar bill for your own car.
| Stack | Pays for others (BI/PD) | Pays for your car | Typical deductible? |
|---|---|---|---|
| Liability only (minimum or higher BI/PD) | Yes, up to limits | No | Usually none on liability |
| “Full coverage” (liability + collision + comprehensive) | Yes | Yes, for covered causes, minus deductible | Yes on collision/comprehensive |
| Financed / leased vehicle | Required at least at state minimums (often higher by lender) | Lender almost always requires collision + comprehensive | Lender may cap maximum deductible |
3. Do you need liability or full coverage in Texas?
Texas financial-responsibility rules center on liability (or another accepted proof). Collision and comprehensive are optional under state law but commonly required by a lienholder if the vehicle is financed or leased. Practical patterns:
- Newer or financed vehicle — expect full physical-damage requirements from the lender.
- Paid-off, lower-value vehicle — some drivers choose liability only and self-insure repairs if they can absorb a total loss.
- Higher assets or multi-car household — many raise BI/PD above 30/60/25 and keep UM/UIM regardless of physical damage.
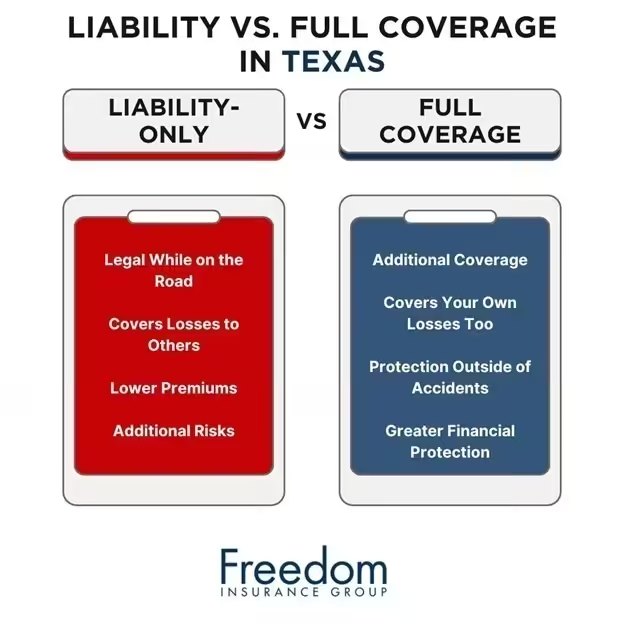
Liability-focused drivers still decide
- Keep continuous BI/PD at or above Texas minimums
- Raise limits if lawsuit exposure exceeds 30/60/25
- Consider UM/UIM for underinsured crash partners
- Accept that your own car repairs are on you
Full-coverage drivers still decide
- Deductible size vs. premium tradeoff
- Whether rental reimbursement is worth adding
- Glass and hail exposure in your county
- Gap coverage if you owe more than ACV
If you owe more than the car’s actual cash value, ask about GAP coverage in Texas—it is separate from “full coverage” and can matter after a total loss.
Self-insure means you are willing and able to pay for repair or replacement from savings if your car is damaged or totaled. Actual cash value (ACV) is generally the car’s market value just before the loss. If you could not absorb that amount without stress, keeping collision and comprehensive may still be the better risk decision even on an older paid-off vehicle. Guaranteed Asset Protection (GAP) is a separate contract that can help with loan balance after a total loss—it is not collision.
4. When Full Coverage Makes Sense in Texas
Financing or Leasing
If you have a car loan or lease, the lender almost always requires collision and comprehensive until the loan is paid off, often with a maximum deductible. Dropping them can lead the lender to buy expensive force-placed coverage and add it to your loan.
New Vehicle
A new or nearly new car loses value quickly but still costs a lot to repair or replace. Full coverage protects that value, and some drivers add gap coverage if they owe more than the car is worth. The Texas Department of Insurance notes that a policy usually covers a newly bought car for about 20 days, so call your agent right away after a purchase.
Young Drivers
Inexperienced drivers have more crashes, so the chance of using collision coverage is higher. If a teen drives an older car of modest value, liability-only can make sense; if the car would be hard to replace, keep full coverage.
Financial Protection
The cost difference is real. Experian’s September 2026 data puts the average Texas full coverage policy at $2,897 a year ($241 a month) and minimum coverage at $1,680 a year ($140 a month). If you could replace your car from savings without hardship, liability-only may be reasonable; if not, the extra premium buys real protection.
5. UM/UIM and PIP: do not forget them in the comparison
Texas insurers generally must offer UM/UIM and PIP; you may reject them in writing. UM/UIM helps when the at-fault driver has no insurance—or not enough. PIP can help with medical bills and related expenses within policy terms, regardless of fault. Dropping UM/UIM to “win” a premium race is a different risk decision than dropping collision on a low-value paid-off car. Keep UM/UIM and PIP selections identical when you compare carriers. Shopping framework: compare car insurance in Texas.
Written rejection means you signed a form declining UM/UIM or PIP as the carrier’s process requires. If you never rejected them, check the declarations—those coverages may already be on the policy. When shopping, match the same accept/reject choices across every quote so you are not comparing a stack that includes PIP to one that does not.
Medical bills after a crash can involve health insurance, PIP, MedPay-style options (when offered), and liability claims against another driver. PIP is not a substitute for health insurance, and dropping it to shave premium is a medical-expense risk decision—not the same choice as dropping collision on a low-value car you can afford to replace.
6. Cost
Liability-only premiums are usually lower than a full stack because collision and comprehensive add claim pathways and deductibles. Exact prices depend on garaging ZIP, driving record, vehicle, credit-based insurance scoring where allowed, prior insurance, and chosen limits—not a single statewide number. Compare identical stacks (same BI/PD, same deductibles, same options). Qualify for discounts you actually earn; do not trust unsupported percentage discounts.
Garaging ZIP is where the vehicle is primarily kept overnight; it drives territory rating. Hail and theft patterns vary across Texas metros and smaller counties, which is one reason comprehensive deductibles deserve a deliberate choice—not whatever number appeared on the first quote. Match deductibles and optional coverages before you rank premiums.
Prior claims and insurance history also feed pricing. Dropping to liability only for a season and then buying collision again later is a risk decision about the car—not a guaranteed path to lower long-term cost. Compare real quotes for the stack you intend to keep.
7. Practical steps this week
Use this list as a short review agenda with your declarations page and loan paperwork in hand:
- Confirm BI/PD on the declarations — at least 30/60/25 continuous coverage for registered on-road use.
- Ask the lender what physical damage and deductible caps are required if you finance or lease.
- Price collision/comprehensive deductibles you could actually pay after a hailstorm or crash.
- Review UM/UIM and PIP as separate elections—not assumptions inside “full coverage.”
- Compare apples-to-apples quotes across carriers with the same limits and deductibles.
FAQs
Is full coverage required in Texas?
State financial-responsibility rules focus on liability. Full physical damage is optional unless a lender or lease contract requires collision and comprehensive.
Does liability insurance fix my car?
No. Liability pays others for injury and property damage you cause (up to limits). Your own vehicle needs collision/comprehensive—or your own funds.
What does 30/60/25 mean?
Common shorthand for $30,000 BI per person / $60,000 BI per accident / $25,000 PD per accident. Confirm the numbers printed on your declarations and current TDI consumer guidance. The Texas Department of Insurance (TDI) publishes consumer materials on financial responsibility.
Is “full coverage” one product?
No. It is a nickname for a package that usually includes liability, collision, and comprehensive—and may include other options such as PIP, UM/UIM, roadside, or rental reimbursement. Always read the declarations.
Will dropping coverages always lower my premium a lot?
Removing collision and comprehensive usually lowers premium, but the amount varies by vehicle, ZIP, and carrier.
Is 30/60/25 enough liability?
It meets the common legal floor, but a serious injury claim can exceed it. Consider higher bodily injury and property damage if you have assets to protect. An umbrella policy can add more protection once your auto liability limits meet its requirements.
Does full coverage include uninsured and underinsured motorist automatically?
Not necessarily. Ask for uninsured and underinsured motorist (and personal injury protection) by name on every quote. Your declarations page lists each coverage you carry, so check it rather than relying on the label.
Can I drop collision after I pay off the car?
Often yes, if the lender is gone and you accept the risk of repairing or replacing the car yourself. Comprehensive for hail/theft is a separate judgment call. Compare the yearly cost of the coverage with the car’s value before deciding.
Where can I verify requirements?
Use the Texas Department of Insurance consumer guides and confirm lender contract language before you change coverages. Your lender can confirm in writing which coverages and deductibles the loan requires.
