

Texas · Homeowners · Pool Insurance
Pool insurance in Texas is rarely a stand-alone product for a typical backyard pool. Most owners protect the pool through a homeowners or, for some rentals, a dwelling policy—covering property damage to the pool and equipment after a covered peril, plus liability and medical payments to others if someone is hurt. Fencing, local ordinances, freeze care, and how the pool is classified (in-ground vs. above-ground) all matter. This guide is educational—not legal advice or a guarantee of coverage on any claim.
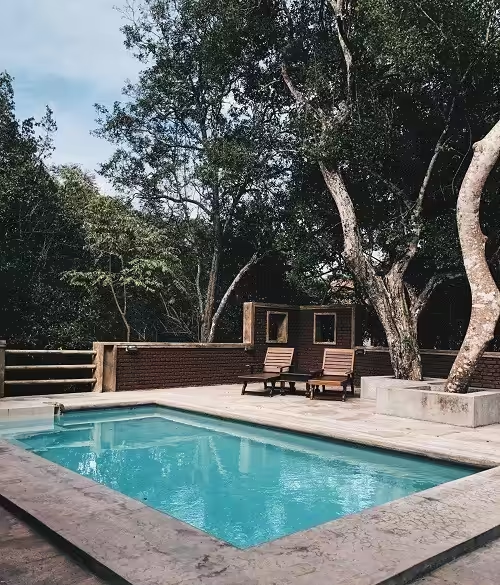
A backyard pool is one of the most enjoyable features a Texas home can have, especially through long summers. It is also a feature insurance companies pay close attention to, because it adds both property value that can be damaged and a place where guests can be hurt. Many homeowners assume they need a special “pool policy,” while others assume their existing coverage handles everything automatically. The reality usually sits in between. In most cases, the pool is protected through the homeowners or dwelling policy you already carry, but how well it is protected depends on how the pool is classified, how the policy is written, and what safety measures are in place.
About percentage discounts: Adding a pool can change premium because it changes risk—not because of a universal fixed-percent “pool discount” or “save X%” claim. Compare forms, liability limits, and safety credits your carrier actually offers; never rely on marketing percentages that are not on your quote.
1. Two jobs: property damage and liability
Property (pool & equipment)
In-ground pools are often treated like other structures (Coverage B) or, depending on construction and the form, as part of the dwelling. Above-ground pools are frequently personal property. Pumps, filters, heaters, and covers generally follow the same peril rules—covered causes of loss only, subject to deductibles and exclusions (including some freeze or maintenance-related losses).
Coverage B, often called other structures coverage, protects structures on the property that are not attached to the house, such as fences, sheds, and in many cases an in-ground pool. Its limit is often set as a share of the dwelling limit, so it is worth checking whether that amount would be enough to rebuild the pool and its surrounding features.
Liability & medical payments
Guest injuries, drownings, and slip-and-falls can implicate personal liability (Coverage E) and medical payments to others (Coverage F). Limits matter; households with high exposure often consider an umbrella after the homeowners policy limits.
Coverage E pays for injuries or damage you are legally responsible for, while Coverage F can pay smaller medical bills for guests no matter who was at fault. An umbrella policy adds extra liability protection above the homeowners limits.
More on how Section II (the liability part of a homeowners policy) works for Texas families: personal liability coverage · party and guest context: liability for homeowners hosting gatherings.
| Item / situation | Typical homeowners policy treatment (verify on your forms) |
|---|---|
| In-ground pool shell | Often other structures / building-related; rebuild cost can exceed a modest Coverage B percentage of A—confirm limits. |
| Above-ground pool | Frequently personal property; special limits or scheduling may apply for higher-value setups. |
| Pumps, filters, heaters | Usually follow the pool’s classification; mechanical breakdown may need separate equipment coverage. |
| Guest injury at the pool | Coverage E liability; Coverage F may help with limited medical payments without proving fault. |
| Rental property with pool | May need a dwelling / landlord form rather than an owner-occupied homeowners form—ask before you assume a homeowners policy applies. |
The table shows why “Is my pool covered?” has more than one answer. The pool shell, an above-ground setup, the equipment, and an injury to a guest can each be handled by a different part of the policy, with its own limit and rules. Mechanical breakdown, such as a pump motor that simply wears out, is usually treated differently from damage caused by a storm or fire, and it may need separate equipment coverage. Reviewing each row against your own declarations page helps you find gaps before summer rather than after a loss.
2. Fencing, ordinances, and “attractive nuisance”
Texas cities and homeowners associations often require barriers, self-closing gates, and other safety features. Insurance underwriting frequently mirrors those expectations. Beyond ordinances, pools can be treated as an attractive nuisance—features that may draw children onto the property—raising the stakes for fencing and supervision. See how Texas homeowners protect against an attractive nuisance.
- Barrier height and latch standards — follow local code and carrier guidelines
- Self-closing / self-latching gates — commonly expected
- Alarm and cover options — may help risk management; ask whether your carrier recognizes them
- Diving boards and slides — some carriers restrict or decline these features
An attractive nuisance is a feature on a property that is likely to draw children who may not understand the danger. Because a pool fits that description, owners can face a higher standard of care, which is why fences, locked gates, and covers matter so much. Diving boards and slides add a further layer of risk, and some insurance companies limit or decline coverage for them. If your pool has one of these features, ask how your insurance company treats it before you assume it is covered.
Insurance does not replace safe pool rules, adult supervision, or compliance with city or homeowners association requirements.
Clear house rules, constant adult supervision when children are swimming, and keeping rescue equipment near the water all reduce the chance of an accident. Those habits protect your guests first, and they also support your insurance position if something does go wrong.
3. Homeowners vs. dwelling forms
Owner-occupied homes with a primary residence usually sit on a homeowners form (often HO-3, the most common form for owner-occupied houses). Investment or non-owner-occupied dwellings may use a dwelling fire / landlord style form with different liability packages. If tenants or short-term guests use the pool, confirm:
- Whether the form includes adequate liability
- Whether pool equipment is scheduled or limited
- Whether the lease and your insurance expectations align
The difference matters most for landlords and short-term rental owners. A homeowners form is generally written for the owner who lives in the house, while a dwelling form is written for a home rented to others. Dwelling forms often include less liability coverage by default, or none at all, unless it is added. If tenants or short-term guests swim in the pool, you will want liability limits that fit that use, and a lease that sets clear pool rules and responsibilities.
For dwelling structure concepts more broadly: dwelling coverage · hub overview: homeowners insurance coverage.
4. Weather, freeze, and maintenance gaps in Texas
Hail, wind, and sudden weather can damage covers, fencing, and above-ground setups. Freeze events in Texas are a recurring lesson: poorly winterized plumbing and equipment can lead to disputes over maintenance vs. covered peril. Keep records of:
- Winterization and open/close service invoices
- Photos of fencing and gates after storms
- Equipment serial numbers and replacement estimates
- Any ordinance upgrades required after a loss
Texas winter storms have shown how quickly freezing temperatures can damage pool plumbing and equipment that is not protected. When a claim is filed, the insurance company may look at whether the damage came from a sudden covered event or from a lack of maintenance, such as leaving equipment exposed during a freeze warning. Keeping service records, photos, and invoices helps show that the pool was properly maintained, which can make a meaningful difference in how a claim is resolved.
Ordinance or law coverage (code upgrades) can matter if a damaged barrier or electrical setup must be rebuilt to current code—ask how your form handles that.
Pool safety codes often change over time, and a fence or electrical system that met the rules when it was built may not meet them today. If a covered loss forces you to rebuild, ordinance or law coverage can help with the added cost of bringing those parts up to current code.
5. Practical checklist for Texas pool owners
- Confirm the pool is listed on your declaration page
- Check Coverage B (or personal property) limits against rebuild/replace cost
- Review Coverage E and F limits; consider umbrella if exposure is high
- Document fencing, gates, and safety features with dated photos
- Ask about restrictions on diving boards, slides, or rental use
- Update the agent after major equipment upgrades
- Never assume “pool insurance” is a separate policy unless your agent confirms one
Going through this checklist once a year, ideally before swimming season starts, keeps your coverage aligned with your pool. It also gives you a chance to update your agent about new equipment, a resurfaced pool, or added features like a slide or outdoor kitchen. Each of those changes can affect both the value of what you need to protect and the liability you carry when guests visit.
Most Texas pools are insured through the homeowners or dwelling policy already on the home, not through a separate pool policy. Make sure the pool is disclosed, check that other structures or personal property limits fit the cost to replace it, keep liability and medical payments limits strong, maintain fencing and gates, and keep records of maintenance and freeze protection. A licensed agent can review how your policy treats the pool and whether an umbrella policy makes sense for your household.
Frequently asked questions
Do I need a separate pool insurance policy in Texas?
Usually no for a typical residential pool. Coverage is typically arranged through homeowners or dwelling forms, sometimes with endorsements. Specialty situations (commercial pools, clubs) are different. Your agent can confirm whether any endorsement would strengthen coverage for your particular setup.
Does homeowners insurance cover pool equipment?
Often yes for covered perils, subject to how the equipment is classified and to deductibles/exclusions. Mechanical breakdown and wear-and-tear are commonly limited or excluded. Keeping serial numbers and purchase records makes equipment claims easier.
Will a pool raise my premium by a fixed percent?
Premiums can change with added risk, but there is no universal fixed-percent increase or discount you should trust from marketing copy. Your quote is the only number that counts. Asking for quotes with and without the pool listed can show its real effect.
What if my rental property has a pool?
Confirm you are on the right form (often dwelling/landlord rather than an owner-occupied homeowners form) and that liability limits match how tenants and guests use the pool. A clear lease that spells out pool rules can also help manage the risk.
Where should I start on this site?
Read pools and Texas homeowners coverage, sizing Texas home coverage, and the Texas homeowners hub. Those pages explain the basics before you speak with an agent.
Does homeowners insurance cover pool collapse for Texas residents?
Sometimes. A sudden collapse caused by a covered peril, such as a falling tree, may be covered under other structures or personal property for an above-ground pool. Collapse from settling, ground movement, wear and tear, or poor maintenance is usually excluded. Read your policy’s collapse and earth-movement provisions.
Do above-ground pools collapse often?
Failures usually trace back to an uneven base, corroded walls or frames, damaged liners, or overfilling, which is why upkeep matters. Damage to a neighbor’s property or injuries caused by a collapse could fall under your liability coverage, so tell your insurer about the pool.
What are the pool insurance requirements for Texas homeowners?
Texas law doesn’t require pool insurance, and the Texas Department of Insurance notes that home insurance itself isn’t legally required, though lenders require it. Many companies set their own conditions, such as a locked fence or no diving board, so disclose the pool and its features when you buy or renew.
Sources & further reading
- Are swimming pools covered by homeowners insurance in Texas?
- Texas homeowners insurance
- Homeowners insurance coverage overview
- Attractive nuisance and Texas homeowners
- Personal liability for Texas families
- Party liability for homeowners
- Texas umbrella insurance facts
- Dwelling coverage
- How to determine home insurance in Texas
- Ask an agent
- TDI — Homeowners insurance guide.
