

Colorado · RV & Travel Trailer · Liability · Storage
Travel trailer insurance in Colorado is about matching liability, physical damage, and usage—weekend camping in the Rockies is not the same risk as full-timing or leaving a trailer in storage through a mountain winter. This educational guide covers liability, comprehensive-style physical damage, seasonal vs full-timer needs, and storage questions for Colorado owners. It is not a binder or a quote. Getting the usage description right on the application—weekend Rockies camping, full-timing, or long winter storage—prevents the most common mismatches between the policy and real Colorado life.
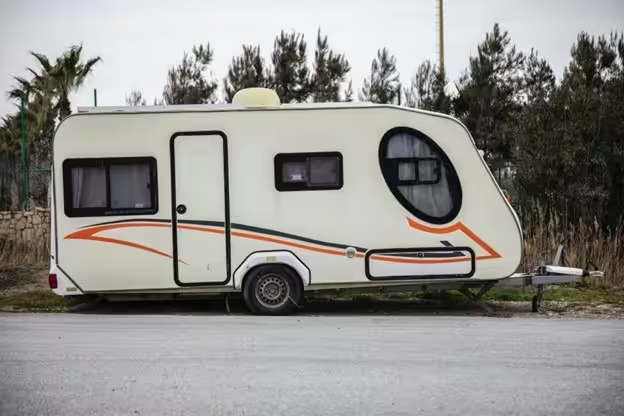
Colorado travel trailers sit at the intersection of auto and recreational-vehicle insurance. While you are towing on mountain grades, liability questions often start with the tow vehicle’s auto policy. While you are parked at a campground or stored through a Front Range winter, physical damage, contents, and personal liability can look more like a RV or trailer form conversation. Mixing those ideas up is how owners discover gaps after a jackknife, a hailstorm, or a theft from a storage lot.
Educational only: Tow vehicle auto policies, RV specialty forms, and campground rules differ. Confirm whether the trailer is scheduled on an auto policy, a separate RV form, or needs full-timer endorsements.
1. Liability: you, the tow vehicle, and the trailer
When you tow a travel trailer on I-70, US-285, or mountain passes, liability questions often start with the tow vehicle’s auto policy—and whether the trailer’s damage to others is addressed there, on a trailer endorsement, or on a dedicated recreational vehicle policy. Campground incidents (someone trips on your gear, a propane mishap, a slide-out issue) may need liability limits and personal liability extensions that a minimal auto form never contemplated.
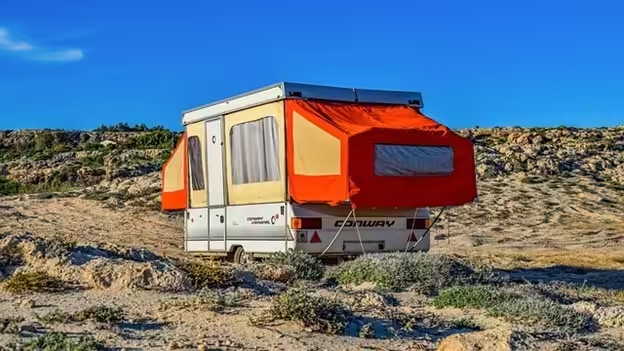
Ask separate questions for connected travel and for parked time at a site. Guests, pets, recreational equipment, and propane use can create liability scenarios a minimal auto form never contemplated. If you carry an umbrella policy, confirm that underlying auto and recreational vehicle limits meet the umbrella carrier’s requirements so the higher layer can actually respond.
- Ask how liability applies while connected vs parked at a site
- Confirm guests, pets, and recreational equipment are discussed on the application
- Umbrella coverage can matter for higher limits—see whether underlying recreational vehicle/auto limits qualify
Mountain driving adds another layer. Steep grades, sudden weather, and wind on high passes increase the chance of an incident involving other vehicles or roadside property. Make sure the people who tow the unit are listed correctly and that the agency knows how often the trailer moves, not only where it is stored in January.
2. Does Colorado Require a Travel Trailer To Carry Separate Insurance?
Colorado requires liability insurance on motor vehicles: at least $25,000 per person and $50,000 per accident for bodily injury and $15,000 for property damage (C.R.S. §10-4-620). A travel trailer has no engine, so the liability that matters is on the vehicle towing it. That liability generally does not pay for damage to the trailer itself or the belongings inside, which is why owners buy separate RV coverage for the trailer, and why lenders require comprehensive and collision on a financed one.
3. Physical damage: collision and comprehensive themes
Travel trailers face hail, wind, theft of contents, collision while towing, and parking-lot mishaps. Specialty recreational vehicle or trailer policies often blend collision and comprehensive-style protections with options for personal belongings, awnings, and attached equipment. Deductibles may differ from your auto. Colorado’s hail and wind seasons make physical damage coverage a frequent talking point for Front Range and eastern plains owners.
| Topic | What to clarify |
|---|---|
| Liability | Limits while towing and while parked; who is an insured |
| Collision / upset | Damage from overturns, jackknife events, and tow-related crashes |
| Comprehensive-style | Hail, theft, vandalism, falling objects, certain weather losses |
| Contents / attachments | Furniture, electronics, awnings, solar—sublimits are common |
| Roadside / towing | Whether trailer-specific roadside differs from auto roadside |
Colorado owners should pay special attention to hail and wind seasons, because trailers parked in driveways or storage lots on the Front Range and eastern plains are exposed. Deductibles on a specialty recreational vehicle or trailer form may differ from your auto deductibles. Contents and attached equipment often have sublimits, so expensive electronics, awnings, or solar gear may need a closer look than the trailer shell alone.
Quiet Colorado auto companions: comprehensive · collision · liability auto.
4. Full-timers vs seasonal campers
Usage is an underwriting fact, not a lifestyle label you can stretch. Seasonal owners who camp on weekends and store the unit most of the year present a different risk than full-timers who live in the trailer as a primary residence. Full-timer forms may address personal liability and belongings more like a housing conversation. Mis-classifying nights occupied is a common application error.
Seasonal owners who store the trailer most of the year and camp on weekends often need different underwriting than full-timers who live in the unit as a primary residence. Full-timer policies may address personal liability more like a homeowners conversation, vacation liability away from a stick-built home, and belongings limits that match full-time living. Mis-classifying usage is a common application error—tell the agency how many nights you actually occupy the trailer.
Seasonal / recreational
Weekend and vacation use; storage address matters; tow vehicle auto policy still central when moving the unit.
Full-timer
Primary residence use; ask about full-timer endorsements, liability, and whether a separate renters or homeowners policy still applies somewhere.
Related context from Freedom’s recreational vehicle education library: full-time recreational vehicle insurance themes · year-round recreational vehicle coverage questions (concepts travel; Colorado forms still control).
If you still keep a stick-built home or rent an apartment somewhere, say so. Full-timing does not always erase every other housing policy question, and agents need the full picture to avoid overlapping or missing liability coverages.
5. Storage, winterization, and Colorado winters
Storage address matters as much as the travel itinerary. A home driveway, paid lot, or resort each carries different theft, hail, freeze, snow-load, and flood exposures. Ask whether laid-up credits exist, what winterization expectations are, and whether contents remain covered while the unit is idle. Photo inventory before storage season is cheap preparation for a later claim.
Parked trailers in Colorado face freeze risk, snow load on roofs and awnings, rodent damage, and theft from storage lots. Tell your insurer the storage address (home driveway, paid lot, or resort). Ask whether laid-up or storage credits exist, what winterization expectations are, and whether contents are covered while the unit is idle. Photo inventory of interior gear before storage season helps if you ever claim.
- Document the vehicle identification number, hitch, and serials for portable generators or bikes
- Confirm whether the storage facility’s contract shifts risk to you
- Ask about flood or flash-flood exposure if you store near drainages
- Update the policy when you move the unit between summer sites and winter storage
6. Tow vehicle, weight ratings, and mountain driving
Colorado mountain grades, wind, and sudden weather demand correct hitch classes, brake controllers, and tow ratings. Insurance applications often ask about gross vehicle weight rating and whether you pull within the tow vehicle’s rated capacity. Pair trailer coverage conversations with the tow vehicle’s auto policy—see Colorado car insurance options and full coverage auto in Colorado.
Honesty on weight and hitch setup protects you twice: once on the road, and again on the application. Pulling beyond the tow vehicle’s rated capacity is a safety problem and an underwriting problem. Confirm brake controllers, weight distribution, and hitch class when you review both the trailer policy and the tow vehicle’s auto form.
Travel trailer insurance in Colorado works best when liability while towing, physical damage while parked, real usage (seasonal vs full-time), and winter storage details all match the policy you buy. Describe the unit and the way you use it accurately, then compare forms on those facts—not on a generic recreational-vehicle slogan.
Frequently asked questions
Does my Colorado auto policy automatically cover my travel trailer?
Sometimes partially for liability while towing—often not enough for the trailer’s physical damage or contents. Ask specifically; many owners add a trailer/recreational vehicle form. Many owners need a separate trailer or recreational-vehicle form for physical damage and contents.
Do I need coverage when the trailer is in storage?
Physical damage and theft can still happen while parked. Storage credits or laid-up options vary—do not assume “parked” means “uninsured on purpose.” Ask about storage credits without assuming that parked means intentionally uninsured.
Is full-timer insurance the same as homeowners?
No, but it can address similar liability and belongings needs for people who live in the recreational vehicle. Classify usage accurately on the application. Classify how many nights you occupy the unit so the application matches real use.
How much does travel trailer insurance cost?
Often a few hundred dollars a year. Progressive reports that its customers nationwide paid an average of $588 a year for travel trailer coverage in 2025. Your price depends on the trailer’s value, whether you add replacement cost or full-timer coverage, where you store it, and your deductibles.
Is this personalized advice?
No. Educational consumer information only—not a quote or binder. For a quote or binder, speak with a licensed agent about your tow vehicle, trailer, and Colorado usage.
Sources and further reading
- Colorado recreational vehicle insurance
- recreational vehicle insurance products
- Travel trailer insurance overview
- Full-time recreational vehicle insurance themes
- Year-round recreational vehicle coverage questions
- Colorado car insurance options
- Missouri recreational vehicle insurance (sibling market hub)
- Ask an agent · Auto quote
- C.R.S. §10-4-620 (Colorado minimum liability).
- Progressive — Do you need travel trailer insurance? (2025 average cost).
